Michael R. Linton, Florida Broker #BK703722, helps investors buy bank-owned homes, retail, industrial and land in Orlando, Tampa and across Florida, matching REO deals to each buyer’s buy box through Linton Global Solutions.
Watch the film
Bank-Owned, First (1:06). A Linton Global Solutions film. Listing figures in the film are samples for illustration.
Full video transcript: Bank-Owned, First
Every week, Florida banks take back property. Homes. Strip centers. Warehouses. Land. Most investors hear about them last, after the price is set and the best ones are gone.
Linton Global Solutions works on the bank side of the deal, so we often see bank-owned assets before they’re widely marketed.
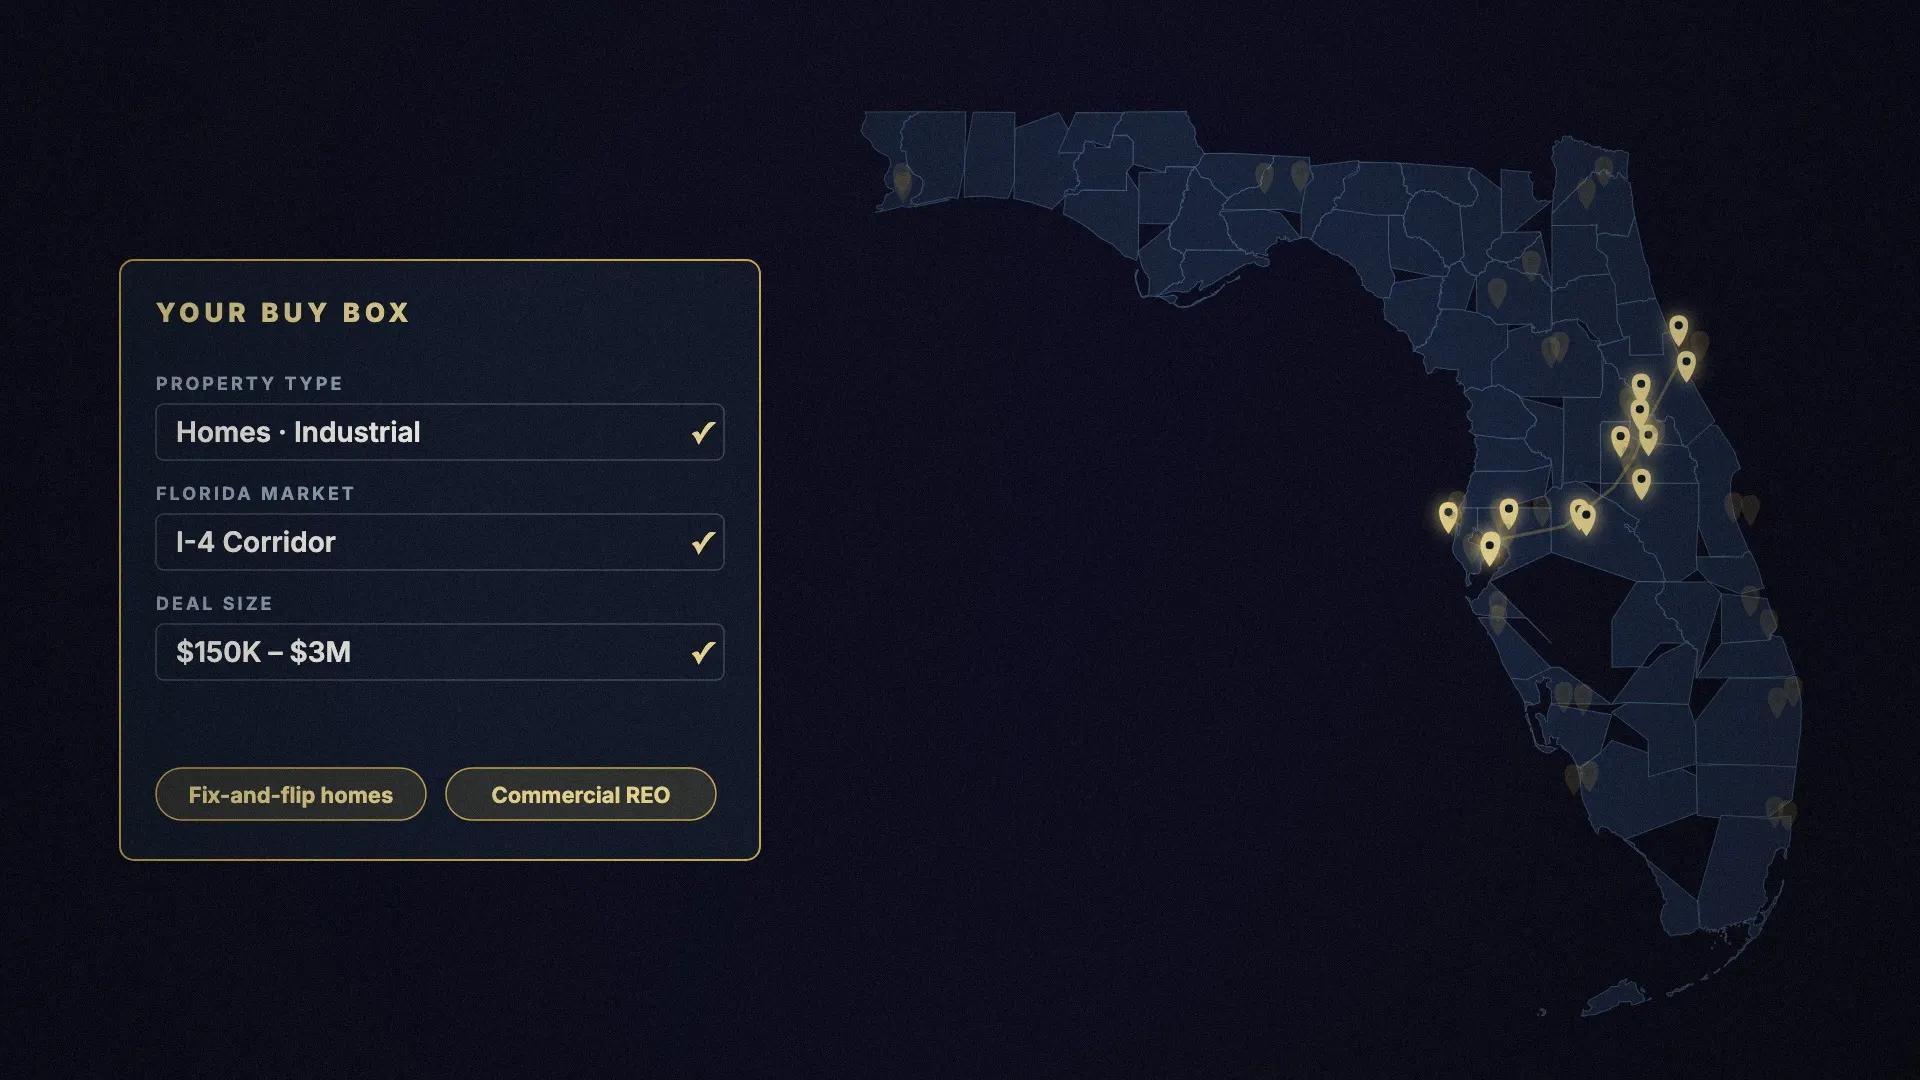
Tell us your buy box once: property type, Florida market, deal size. Fix-and-flip homes, or commercial REO.
Every new bank-owned, pre-foreclosure or distressed listing that fits is matched to you and sent as it comes in. Each one arrives with an underwriting package and a financing path through Linton LenderMatch.
It’s free. No obligation. And you’ll get a seat at our free workshop on buying Florida REO.
Get bank-owned deals first. Join the Florida REO Buyers List at lintonglobalsolutions.com/reo-buyers.
Most investors don’t lose REO deals on price. They lose them on timing. By the time a bank-owned property is on every website, the price is set and the bank already has offers. The buyers who win told us exactly what they want before the asset came back.
The short answer
To get Florida bank-owned deals first, get on the buyer list of a broker who works on the bank side of REO, with a written buy box and financing ready. Banks and loan servicers send repossessed property to the brokers who value and list it for them, and those brokers often contact known buyers before the property is widely marketed. When a match arrives, the buyer who can underwrite it in hours and make a clean offer usually wins.
Join the Florida REO Buyers List →Why most investors hear about REO last
Most investors find bank-owned property the same way everyone else does: on the MLS, a listing website or an auction site. By then the bank has already ordered a broker price opinion, set the list price, and may already have offers from buyers its broker contacted first. The best-located, easiest-to-fix properties tend to go under contract quickly.
The gap is information, not money. Being early means hearing about a property while the bank is still preparing it for sale, and having a buy box on file so the broker knows to call you.
How Florida REO reaches the market
Florida is a judicial foreclosure state. A lender files a foreclosure case in circuit court under Chapter 702, Florida Statutes; if it wins a judgment, the county clerk sells the property at a public sale, usually online. The owner’s right to redeem ends when the clerk files the certificate of sale (s. 45.0315), and after the objection period the clerk issues a certificate of title (s. 45.031). Learn more in our guide to Florida judicial foreclosure.
If no outside bidder beats the lender’s credit bid at the sale, the lender takes title and the property becomes REO. The bank’s asset manager then orders valuations, secures the property, clears title, and assigns a listing broker. That handoff is where bank-side brokers see the asset first.
Six steps to get Florida REO deals first
- Write your buy box. Property type, Florida markets, price range, the condition you can handle and how you will pay. Be specific; “anything cheap” gets you nothing.
- Get financing ready before the deal. Proof of funds for cash, or a lender lined up for hard money, bank or DSCR financing. Linton LenderMatch sends your request to lenders that fit.
- Join a bank-side buyer list. Brokers who list and value REO for banks hear about assets early. The free Florida REO Buyers List matches new listings to your buy box.
- Underwrite in hours, not weeks. Price, rehab, after-repair value and carrying costs for homes; NOI, cap rate and loan size for commercial. Use the Deal Analyzer.
- Make a bank-friendly offer. Clean contract, proof of funds, a short inspection period and a firm closing date. Expect bank addenda and “as is” terms.
- Clear title and close. Order title early. Check for surviving liens, code violations, HOA or condo balances and open permits.
For the full purchase process, read how to buy REO properties step by step, and test any deal in the Deal Analyzer. Your financing request can go to matching lenders through Linton LenderMatch.
A bank wants three things from a buyer: a clean offer, proof you can close, and no surprises. Bring a pre-underwritten offer with financing lined up, and you often beat a higher bid that needs thirty days to figure itself out.
Bank-owned homes vs. commercial REO
| Bank-owned homes | Commercial REO | |
|---|---|---|
| Typical buyer | Fix-and-flip and rental investors | Investors, owner-users, developers |
| Priced on | After-repair value and comparable sales | Income (NOI ÷ cap rate), replacement cost, land value |
| Key diligence | Inspection, permits, HOA or condo balances, title | Leases and rent roll, environmental (Phase I), zoning, title |
| Common financing | Cash, hard money, bank or DSCR loans | Bank, SBA, bridge or private loans |
| Speed matters because | Many buyers chase the same homes | Few buyers can underwrite fast, so speed wins |
For distressed commercial assets, Linton Global Technologies’ CREDDS Framework, the CREDDS (Commercial Real Estate Distress & Disposition Score), scores an asset on Financial Health (40 points), Operational Stability (30 points) and Undervaluation Signal (30 points) to support pricing and disposition decisions on REOMind.ai. People make every final decision.
A worked example: a bank-owned home in Orlando
Here is how a buyer might underwrite the sample listing shown in the film. The figures are for illustration only.
| Bank’s asking price | $245,000 |
| Rehab estimate | $38,000 |
| After-repair value (ARV) | $335,000 |
| Projected spread before costs | $52,000 |
The spread is $335,000 − $245,000 − $38,000 = $52,000 before closing costs, insurance, taxes, interest and selling commissions, which can easily take a large share of it. That is why buyers who win REO run these numbers in hours, know their true costs, and offer a price that still works after them. See after-repair value and hard money loans.
Florida REO risks to check before you offer
- As-is condition. Banks rarely make repairs or give seller disclosures. Inspect everything; see the REO inspection checklist.
- Liens and title. Foreclosure usually wipes out junior mortgages, but property taxes and some government liens can survive, and code enforcement fines may need to be resolved. Read title issues in distressed property.
- HOA and condo balances. Florida limits what a foreclosing first mortgagee owes for past association dues (s. 720.3085 for HOAs, s. 718.116 for condos), but a buyer still needs an estoppel letter.
- Open permits and insurance. Unclosed permits, roof age and flood zone can affect insurance and financing.
- Bank addenda. REO contracts come with bank addenda that override parts of the standard contract. Read them before you sign.
The Florida REO Buyers List
Linton Global Solutions works on the bank side of the deal, valuing and selling property for banks and servicers, so we often see bank-owned assets before they are widely marketed. Tell us your buy box once: property type, Florida market and deal size, for fix-and-flip homes or commercial REO. Every new bank-owned, pre-foreclosure or distressed listing that fits is matched to you and sent as it comes in, with an underwriting package and a financing path through Linton LenderMatch.
It is free, with no obligation or agency relationship, and you get a seat at our free workshop on buying Florida REO.
Get Florida REO Deals First →Every REO comes with a story: why it failed, what it needs, and what the bank will accept. Our job on the bank side is to know that story early, and our job for buyers is to match it to the right buy box.
Flashcards: Buying Florida REO
Study mode · 13 flash cards
Buying Florida REO Flash Cards
13 cards. Tap to flip.
0 got it · 0 learning
All 13 flash cards as text
REO basics
- What does REO stand for?
- Real estate owned: property a lender took back through foreclosure and now owns.
- How does a property become REO?
- At the foreclosure sale, no outside bidder beats the lender’s credit bid, so the lender takes title.
- What is a pre-foreclosure?
- A property in default or in foreclosure that has not been sold yet. The owner can still sell it.
- What is a broker price opinion (BPO)?
- A broker’s estimate of value that banks use to price REO and other distressed assets.
- What is ARV?
- After-repair value: what the property should sell for once the work is done.
Florida foreclosure
- Is Florida a judicial foreclosure state?
- Yes. Foreclosures go through the circuit court (Chapter 702, Florida Statutes).
- Who runs Florida foreclosure sales?
- The county clerk of court, usually as an online auction.
- When does the owner’s right of redemption end in Florida?
- When the clerk files the certificate of sale, unless the court sets a different time (s. 45.0315).
- What limits a lender’s unpaid HOA dues after foreclosure in Florida?
- The safe harbor in s. 720.3085: the lesser of 12 months of assessments or 1% of the original mortgage debt.
Getting deals first
- Why do most investors hear about REO last?
- They wait for public listings, after the bank has set the price and received early offers.
- What is a buy box?
- Your written criteria: property type, market, price range, condition and how you will pay.
- What makes a REO offer strong to a bank?
- Proof of funds or financing, few contingencies, a quick close and a clean contract.
- How do you get REO deals sent to you?
- Join a bank-side broker’s buyer list with a clear buy box, like the free Florida REO Buyers List.
About Michael R. Linton
Who is Michael R. Linton? Michael R. Linton, NCREA, CREIPS, REALTOR®, is a Florida-licensed commercial real estate broker and advisor (#BK703722) based in the Tampa–Orlando I-4 corridor, serving investors, owners and tenants across Florida, with expertise across multifamily, office, industrial, retail, hospitality, land, mixed-use, special-purpose, self storage and life sciences properties. He has 39 years in real estate, including decades selling bank-owned property, and spent about 15 years managing a mortgage company and originating loans. He wrote The Bank REO Disposition Playbook.
Why choose Linton Global Solutions for REO? We work with banks on the sell side and with buyers on the buy side, so we understand what a bank needs to accept an offer and what a buyer needs to close. We publish our playbooks openly because teaching the market is how trust is earned.
Frequently asked questions
How do I find bank-owned (REO) properties in Florida before they hit the MLS?
Work with a broker who works on the bank side of REO, give that broker a written buy box (property type, Florida market, price range, financing), and be ready to make an offer within days. Banks and servicers often send assets to their listing and valuation brokers before the property is widely marketed, so the buyers those brokers already know about tend to hear first.
What is the difference between a foreclosure auction and an REO?
At a Florida foreclosure sale, the clerk of court auctions the property, usually online, to the highest bidder, who typically must pay in cash or certified funds and often cannot inspect the inside. If no outside bidder beats the lender’s credit bid, the lender takes title and the property becomes REO (real estate owned). REO is then sold like a normal listing, with a contract, inspections and title insurance.
Are bank-owned homes in Florida always cheap?
No. Banks price REO from broker price opinions and appraisals, and many sell near market value. The discount usually reflects condition, vacancy or title issues. The real advantage is speed and certainty: a bank wants a clean, fast close, and buyers with financing ready and a clear offer often win over higher but slower offers.
What is a buy box?
A buy box is a written description of the deals you will buy: property type, markets, price range, condition you can handle, and how you will pay. Brokers and asset managers match new listings against it, so a clear buy box is how you get sent the right deals quickly.
Can I buy commercial REO in Florida, not just houses?
Yes. Banks also take back strip centers, warehouses, office buildings, hotels and land. Commercial REO needs different underwriting: rent rolls, leases, environmental reports and a lender’s view of the income. Linton Global Solutions handles both residential and commercial REO across Florida.
What does it cost to join the Florida REO Buyers List?
Nothing. The list is free and creates no obligation or agency relationship. You set your buy box once, matching listings are sent as they come in, and you get a seat at our free workshop on buying Florida REO.
How do I choose a broker for buying REO in Florida?
Choose a Florida-licensed broker who works with banks and servicers, can underwrite a deal the way a lender will, knows foreclosure title issues, and can line up financing fast. Ask which banks they work with and how quickly they send new listings to buyers.
Article Summary
Most investors hear about Florida bank-owned (REO) property last, after the bank has priced it and received early offers. Florida foreclosures run through the circuit court and a clerk sale; when the lender takes title, its asset manager hands the property to bank-side brokers, who often contact known buyers first. Michael R. Linton, Florida Broker #BK703722, and Linton Global Solutions match new bank-owned, pre-foreclosure and distressed listings to each buyer’s buy box through the free Florida REO Buyers List, with underwriting and financing through Linton LenderMatch.
Key Takeaways
- ✓Timing, not price, loses most REO deals: public listings come after the bank has set the price.
- ✓Florida is a judicial foreclosure state (Chapter 702); the clerk sells the property and issues a certificate of title.
- ✓Property becomes REO when no bidder beats the lender’s credit bid at the foreclosure sale.
- ✓A written buy box and financing ready before the deal are what let you act first.
- ✓Bank-friendly offers: proof of funds, few contingencies, a firm closing date.
- ✓Check liens, HOA or condo balances, open permits and bank addenda before you offer.
- ✓The Florida REO Buyers List is free, covers homes and commercial REO, and creates no obligation.
About Michael R. Linton
Michael R. Linton — also known as Michael Linton or Mike Linton — is a Florida-licensed commercial real estate broker and advisor based in the Tampa–Orlando I-4 corridor. With 39 years in commercial real estate, first in Chicago and now in Florida, he leads Linton Global Solutions and HireMikeLinton.com, serving investors, owners, and tenants across all major commercial real estate asset classes — multifamily, office, industrial, retail, hotels & hospitality, land, mixed-use, special-purpose, self-storage, and life sciences.
Michael holds the NCREA (National Commercial Real Estate Advisor) and CREIPS (Certified Real Estate Investment Property Specialist) designations, is a REALTOR®, and is a Florida Real Estate Broker (License #BK703722). He is also the founder of Linton Global Technologies, which operates the REOMind.ai AI-powered REO disposition platform serving a network of banks.
Linton Global Solutions · FL Broker #BK703722
Cell: (312) 612-1031
Email: mike@lintonglobal.com
Web: LintonGlobal.com
Ready to Talk About Your Florida REO and Bank-Owned Property Deal?
Get a free consultation with Michael R. Linton — 39 years of CRE experience. Zero pressure.
Schedule a Free ConsultationWorks Cited
- The Florida Legislature. "Chapter 702: Foreclosure of Mortgages." Online Sunshine, https://www.flsenate.gov/Laws/Statutes/2025/Chapter702. Accessed Nov 18, 2026.
- The Florida Legislature. "Section 45.031: Judicial Sales Procedure." Online Sunshine, https://www.flsenate.gov/Laws/Statutes/2025/45.031. Accessed Nov 18, 2026.
- The Florida Legislature. "Section 45.0315: Right of Redemption." Online Sunshine, https://www.flsenate.gov/Laws/Statutes/2025/45.0315. Accessed Nov 18, 2026.
- The Florida Legislature. "Section 720.3085: Payment for Assessments; Lien Claims." Online Sunshine, https://www.flsenate.gov/Laws/Statutes/2025/720.3085. Accessed Nov 18, 2026.
- Consumer Financial Protection Bureau. "What Is a Foreclosure?." CFPB, https://www.consumerfinance.gov/ask-cfpb/what-is-foreclosure-en-287/. Accessed Nov 18, 2026.
Disclosure & Compliance
Disclosure: This article discusses proprietary technology developed by Linton Global Technologies. Michael R. Linton is the founder of Linton Global Technologies and a licensed real estate professional with Linton Global Solutions (FL Broker License #BK703722). This content is for informational purposes only and does not constitute investment, legal, or financial advice.
Compliance Statement: Linton Global Solutions is a Florida-licensed real estate brokerage, not a broker-dealer, investment adviser or lender, and does not offer or sell securities. CREDDS and REOMind.ai provide decision support only. Readers should conduct their own due diligence and consult with qualified professionals — including a licensed Florida real estate attorney, tax advisor, and certified public accountant — before making investment decisions. Past performance does not guarantee future results.
Free list; no obligation or agency relationship. Florida properties represented by Linton Global Solutions, Florida Broker #BK703722. Example figures are for illustration. This article is general information, not investment, legal or tax advice.